

Over the past few months, I’ve noticed a definite shift in the conversations I’m having with clients, particularly my American clients.
A year or two ago, the questions were mostly practical:
Which region should we choose? How does the buying process work? Can we renovate? How do we get residency?
Now, the conversation often begins somewhere else entirely:
What if global instability worsens? Would Europe be dragged down too? And, in that case, is now a terrible time to buy property in France?
The world does feel uncertain. The IMF’s latest outlook points to slower global growth and renewed inflationary pressures, while the European Commission’s Spring 2026 forecast expects French GDP growth of just 0.8% in 2026, rising slightly to 1.1% in 2027. In other words, nobody serious is pretending we are in a booming economic environment.
But uncertainty does not automatically mean that buying property in France is a bad decision. It simply means the purchase needs to be approached with more discipline, more patience, and a clearer understanding of the risks.
France is not the US or UK property market
One of the biggest mistakes foreign buyers can make is assuming that the French property market behaves like the American or British market.
It doesn’t.
French banks tend to be conservative lenders. Borrowing capacity is closely assessed, mortgage terms are usually controlled, and buyers are not generally encouraged to stretch themselves to the absolute limit.
For foreign buyers, this can sometimes feel frustrating, especially if they are used to a more flexible lending culture. But that caution also helps create a more stable environment overall.
Long-term fixed-rate mortgages are also common in France, which means many homeowners are less exposed to sudden payment shocks when interest rates rise. In markets where variable-rate loans are more common, households can come under pressure much more quickly.
There are practical reasons France is less speculative too. Buying costs are high, the process is relatively slow, and selling quickly is rarely painless. That naturally discourages short-term flipping. Most people buy with a longer horizon, and many French owners still view property as a family asset rather than something to trade in and out of.
This does not make the market immune to global events. Prices can fall. Transactions can slow. Buyers can hesitate. Sellers can become unrealistic.
But France is generally less prone to the kind of rapid boom-and-bust cycles seen in more speculative markets.
In a downturn, the French market often slows before it collapses. Sellers wait. Buyers pause. Transactions fall. Prices adjust — but usually gradually.
For long-term buyers, that distinction matters.
The correction has already happened — at least partly
Let’s not pretend France has avoided difficulty.
The property market went through a painful adjustment in 2023 and 2024, largely driven by higher borrowing costs and reduced purchasing power. Buyers became more cautious, banks became more selective, and transaction volumes fell sharply.
I saw this first-hand while filming my latest House Hunters International episode, which premieres this week and follows a wonderful couple moving from Canada back to Fred’s home country of France.
Their search captured a very real Paris dilemma. Fred wanted the classic Paris lifestyle: the energy of the city, cafés on the corner, beautiful streets, and the feeling of being right in the middle of it all. Richard, quite sensibly, was drawn to the up-and-coming suburbs, where the same budget could offer more space, more breathing room, and a different quality of daily life.
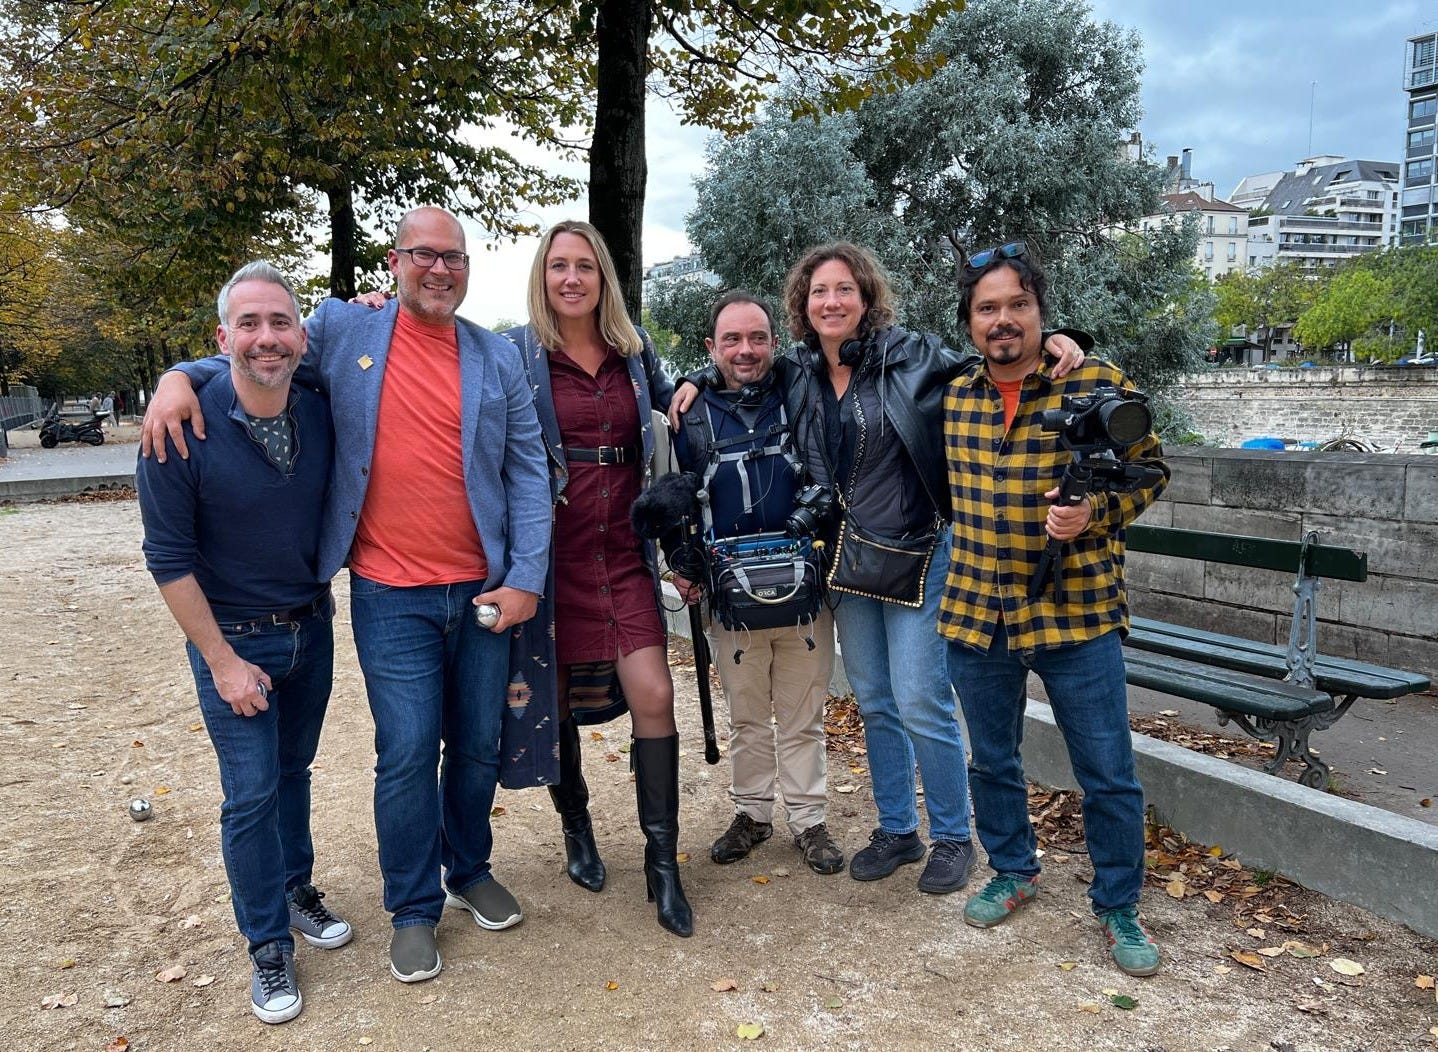
That tension — lifestyle versus space — is exactly where the Paris market has corrected. Paris is still Paris, and nobody is pretending it has suddenly become a bargain. But after the post-Covid highs, higher borrowing costs and more cautious buyers have made the market more measured. Sellers have had to become more realistic, and buyers have had a little more room to ask questions, compare options and negotiate.
To me, that is the key point. What we are seeing is not a dramatic collapse, but a necessary correction after an overheated period and in some cases, a healthier conversation about what people actually want from their French life.
The latest notarial data also suggests France is no longer in freefall. The Notaires de France describe the current phase as a reprise sans excès — a recovery without excess — and say the market has entered a period of stabilisation.
Transaction volumes reached around 958,000 sales over the twelve months to February 2026, up by around 11% year-on-year.
Prices are also not showing signs of a dramatic national collapse. According to the Notaires, projections from preliminary contracts to the end of May 2026 suggest near-stability in older property prices nationally, around -0.2% over one year, with apartments at +0.3% and houses at -0.5%.
That is not a boom, but it is not a crash either.
It is a market where negotiation matters again. Sellers are often more willing to have a realistic conversation, and buyers have more time to compare properties properly, review diagnostics, ask about planning issues, understand energy ratings, assess septic systems and look carefully at renovation budgets.
For foreign buyers, that time is valuable.
In France, the real risk is not simply that the market might fall by a few percent. The bigger risk is buying the wrong property, in the wrong location, with hidden costs or poor resale appeal.
A more cautious market can actually be an advantage if it helps buyers avoid those mistakes.
The question is not “will prices rise next year?”
For most of my clients, buying in France is not a short-term speculative investment.
They are buying a future home, a base in Europe, a retirement plan, a lifestyle, a family project, or simply a place where they can breathe a little more easily.
So the question I encourage them to ask is not:
Will this property be worth more in twelve months?
The better question is:
Would I still be happy owning this property if the market stayed flat for five years?
That one question changes the conversation. It forces buyers to think about the fundamentals.
Is the location strong?
Is the price defensible?
Are the renovation costs realistic?
Is the house manageable?
Will the property appeal to future buyers?
Does the lifestyle value justify the purchase, even without short-term capital growth?
That is a much healthier way to make a decision.
A personal note on why place matters
You may have noticed that I didn’t send a newsletter last week.
I had the pleasure of having my niece, who also happens to be one of my best friends, and her husband to stay, along with their six-month-old bundle of joy. She is currently training him to call me Great Aunt Elle, which makes me sound less like a responsible adult and more like a character from an East End soap opera who knows everyone’s business and always has a cigarette, a gin, and an opinion.
By pure coincidence, my eldest brother was also visiting for his annual fishing trip with our dad, so we made the most of the good weather with BBQs, long chats, and the traditional family sport of putting the world to rights — with absolutely no evidence that the world had asked for our help.
It was lovely. And it reminded me of something that rarely makes it into the property listings.
When you move to another country, you are not just changing your address. You are changing your support network, your daily rhythms, your safety net.
Of course, when you live in France, everyone wants to visit — including, occasionally, people you rather wish had chosen Spain — but it is still not quite the same as having family and old friends around you day to day.
For me, this is one of the most important parts of relocation.
Yes, the house matters. The view matters. The village matters. The market, the bakery, the garden, the shutters — they all matter.
But community matters too.
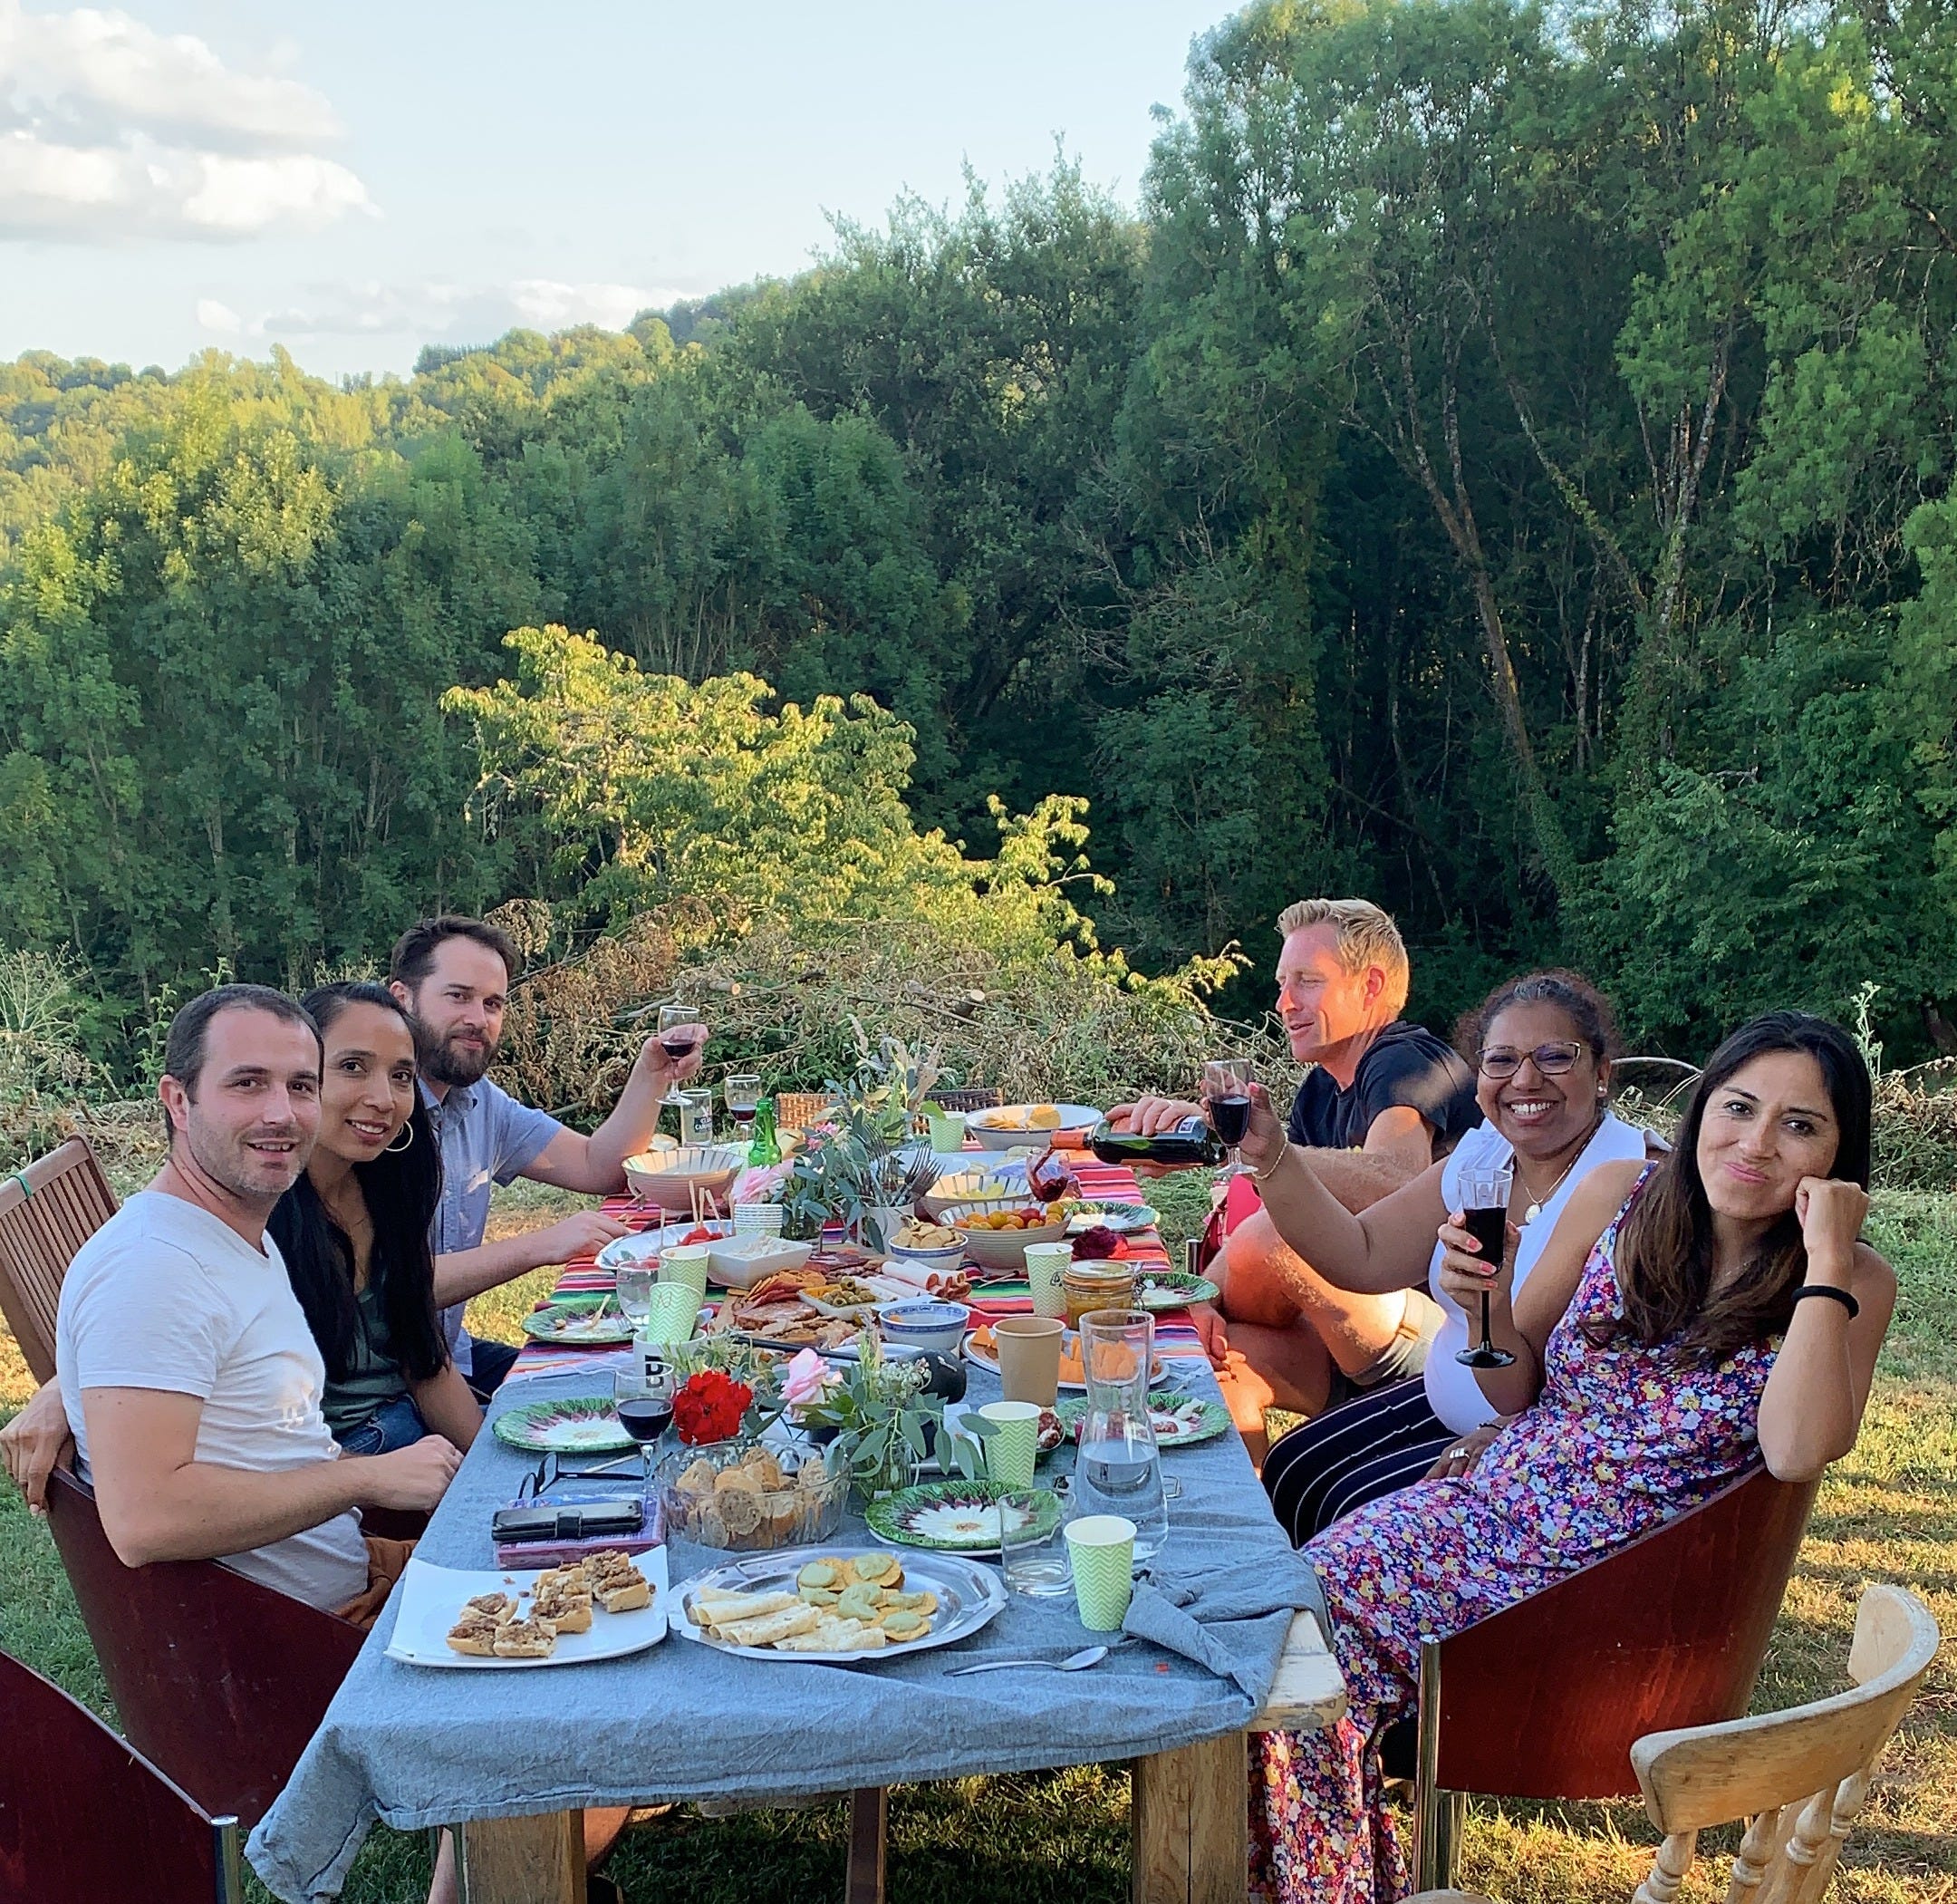
I have always needed to live somewhere where I can build a life, not just own a property. Somewhere with people around me: neighbours, friends, familiar faces, like-minded souls. I am very comfortable in my own company, but there is something deeply reassuring about knowing that community is there when you need it.
That is what many people are really buying when they buy in France.
Not just square metres.
A different rhythm.
A different way of living.
A place to belong.
So, is France still a safe property bet?
My answer is yes — but with caveats.
France is not immune to global events. It is not disconnected from recession risk, interest rates, inflation, energy costs or political uncertainty. Anyone telling you otherwise is oversimplifying.
But nor does the current evidence suggest that France is heading into a dramatic property-market collapse.
The more accurate picture is of a market that has already corrected, is now stabilising, and remains highly dependent on financing conditions, buyer confidence and sensible pricing.
So this is not a market for impulsive buying.
It is a market for thoughtful buying.
If you are looking for a quick flip, I would be cautious. But if you are looking for a long-term lifestyle purchase in one of the most desirable countries in Europe, France still has a great deal to offer.
The key is not to buy out of fear, panic or fantasy.
The key is to buy with clarity.
And that, more than anything, is what I try to give my clients: a clear view of the risks, the opportunities, and the reality on the ground.
À très bientôt,
Eleanor
Very interesting article which explains everything really clearly. Merci Great Aunt Elle!@